The FAFSA, short for the Free Application for Federal Student Aid, is the primary gateway form for federal financial aid. Many states and colleges also use it to award their own need-based grants and scholarships. Even families who assume they will not qualify sometimes find surprises, especially with some scholarships that require a FAFSA on file, federal student loans, and certain school-based grants.
If the process feels intimidating, you are not alone. I have sat with families who speak more than one language at home, families who have never filed for aid before, and families who thought one wrong click would ruin everything. The good news is that FAFSA follows a predictable path. If you take it step by step and gather the right documents first, it becomes very manageable.
One more helpful note up front: some colleges also require the CSS Profile or an additional institutional form to award certain types of institutional aid. FAFSA is still the place to start.
What the FAFSA is
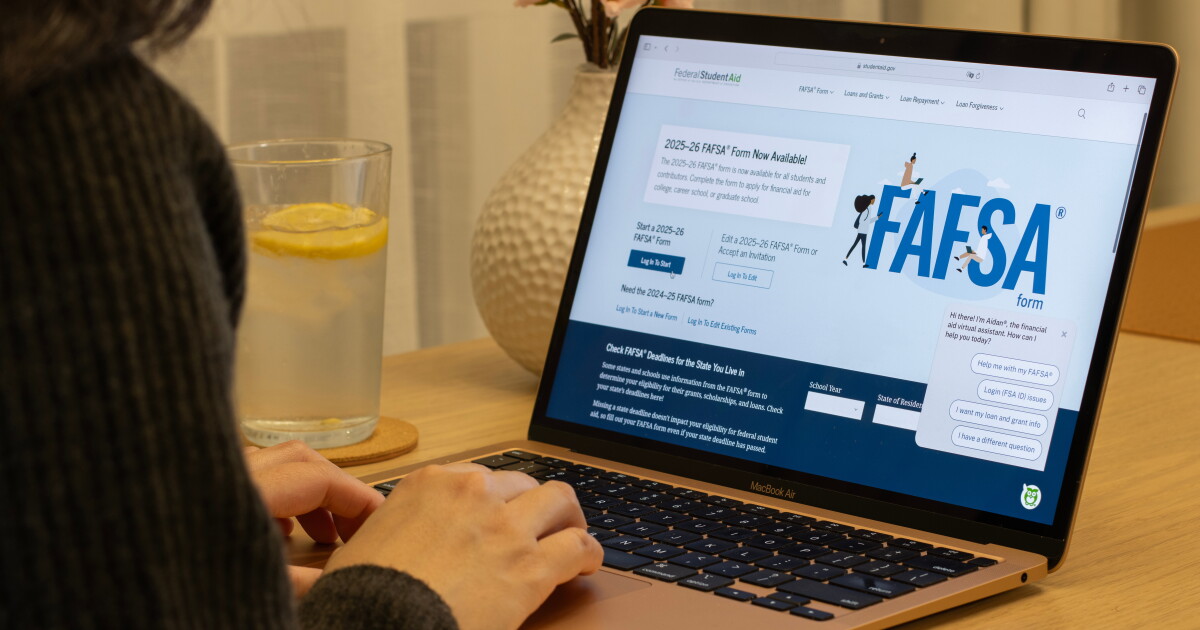
The FAFSA is a federal form that collects basic information about the student and the family’s finances. Schools use it to estimate your eligibility for financial aid, including:
- Federal grants (money that typically does not need to be repaid, like the Pell Grant for eligible students)
- Federal work-study (part-time jobs, often on campus, for eligible students)
- Federal student loans (borrowing options with federal rules and protections)
- State and school aid (many states and colleges use FAFSA data to award their own grants and scholarships)
Important note: FAFSA is not a bill and it does not obligate you to accept any aid offered. Think of it as the application that opens the door.
Also, the FAFSA now produces a number called the Student Aid Index (SAI). You may still see older resources mention the EFC (Expected Family Contribution), but SAI is the updated term schools receive.
Who should file
In general, students should file a FAFSA if they plan to attend any of the following:
- Four-year colleges and universities
- Community college
- Trade and vocational programs
- Many certificate programs at eligible schools
You should strongly consider filing even if:
- You think you will not qualify. Some aid is not strictly need-based, and some scholarships require a FAFSA.
- Your income changed recently. FAFSA is based on prior tax information, but schools can sometimes adjust for major changes through an appeal process.
- You are paying out of pocket. Filing keeps options open if circumstances shift midyear.
Dependent vs. independent
One of the biggest points of confusion is whether a student must include parent information. FAFSA uses federal rules to determine dependency status, and it is not the same as what a family considers independent in everyday life.
Many undergraduates are considered dependent for FAFSA purposes and must provide parent information, even if they live on their own or pay some of their own bills. Some students qualify as independent. Common examples include students who are:
- Age 24+
- Married
- Veterans or currently serving on active duty
- Parents who provide more than half of a child’s support
- In foster care after age 13, or a ward of the court
- Emancipated minors or in a legal guardianship (as determined by a court)
- Unaccompanied and experiencing homelessness, or at risk of homelessness (as determined by an authorized party)
If you are unsure, answer the FAFSA dependency questions carefully and follow the system prompts. Do not guess and skip parent info unless the FAFSA indicates you can.
Before you start
Before you open the application, take 20 minutes to get organized. This reduces errors and makes the whole process faster.
1) Create your FSA ID early
FAFSA is completed online, and each person who must provide information will generally need their own account called an FSA ID. In current FAFSA terms, those people are called contributors (for example, a parent or a spouse if required). Set this up early so you are not troubleshooting identity verification or account recovery close to a deadline.
2) Make a FAFSA folder
Gather what you need in one place. Most families use:
- Social Security numbers (and, if a contributor does not have an SSN, the identifying information the FAFSA requests instead)
- Driver’s license (if applicable)
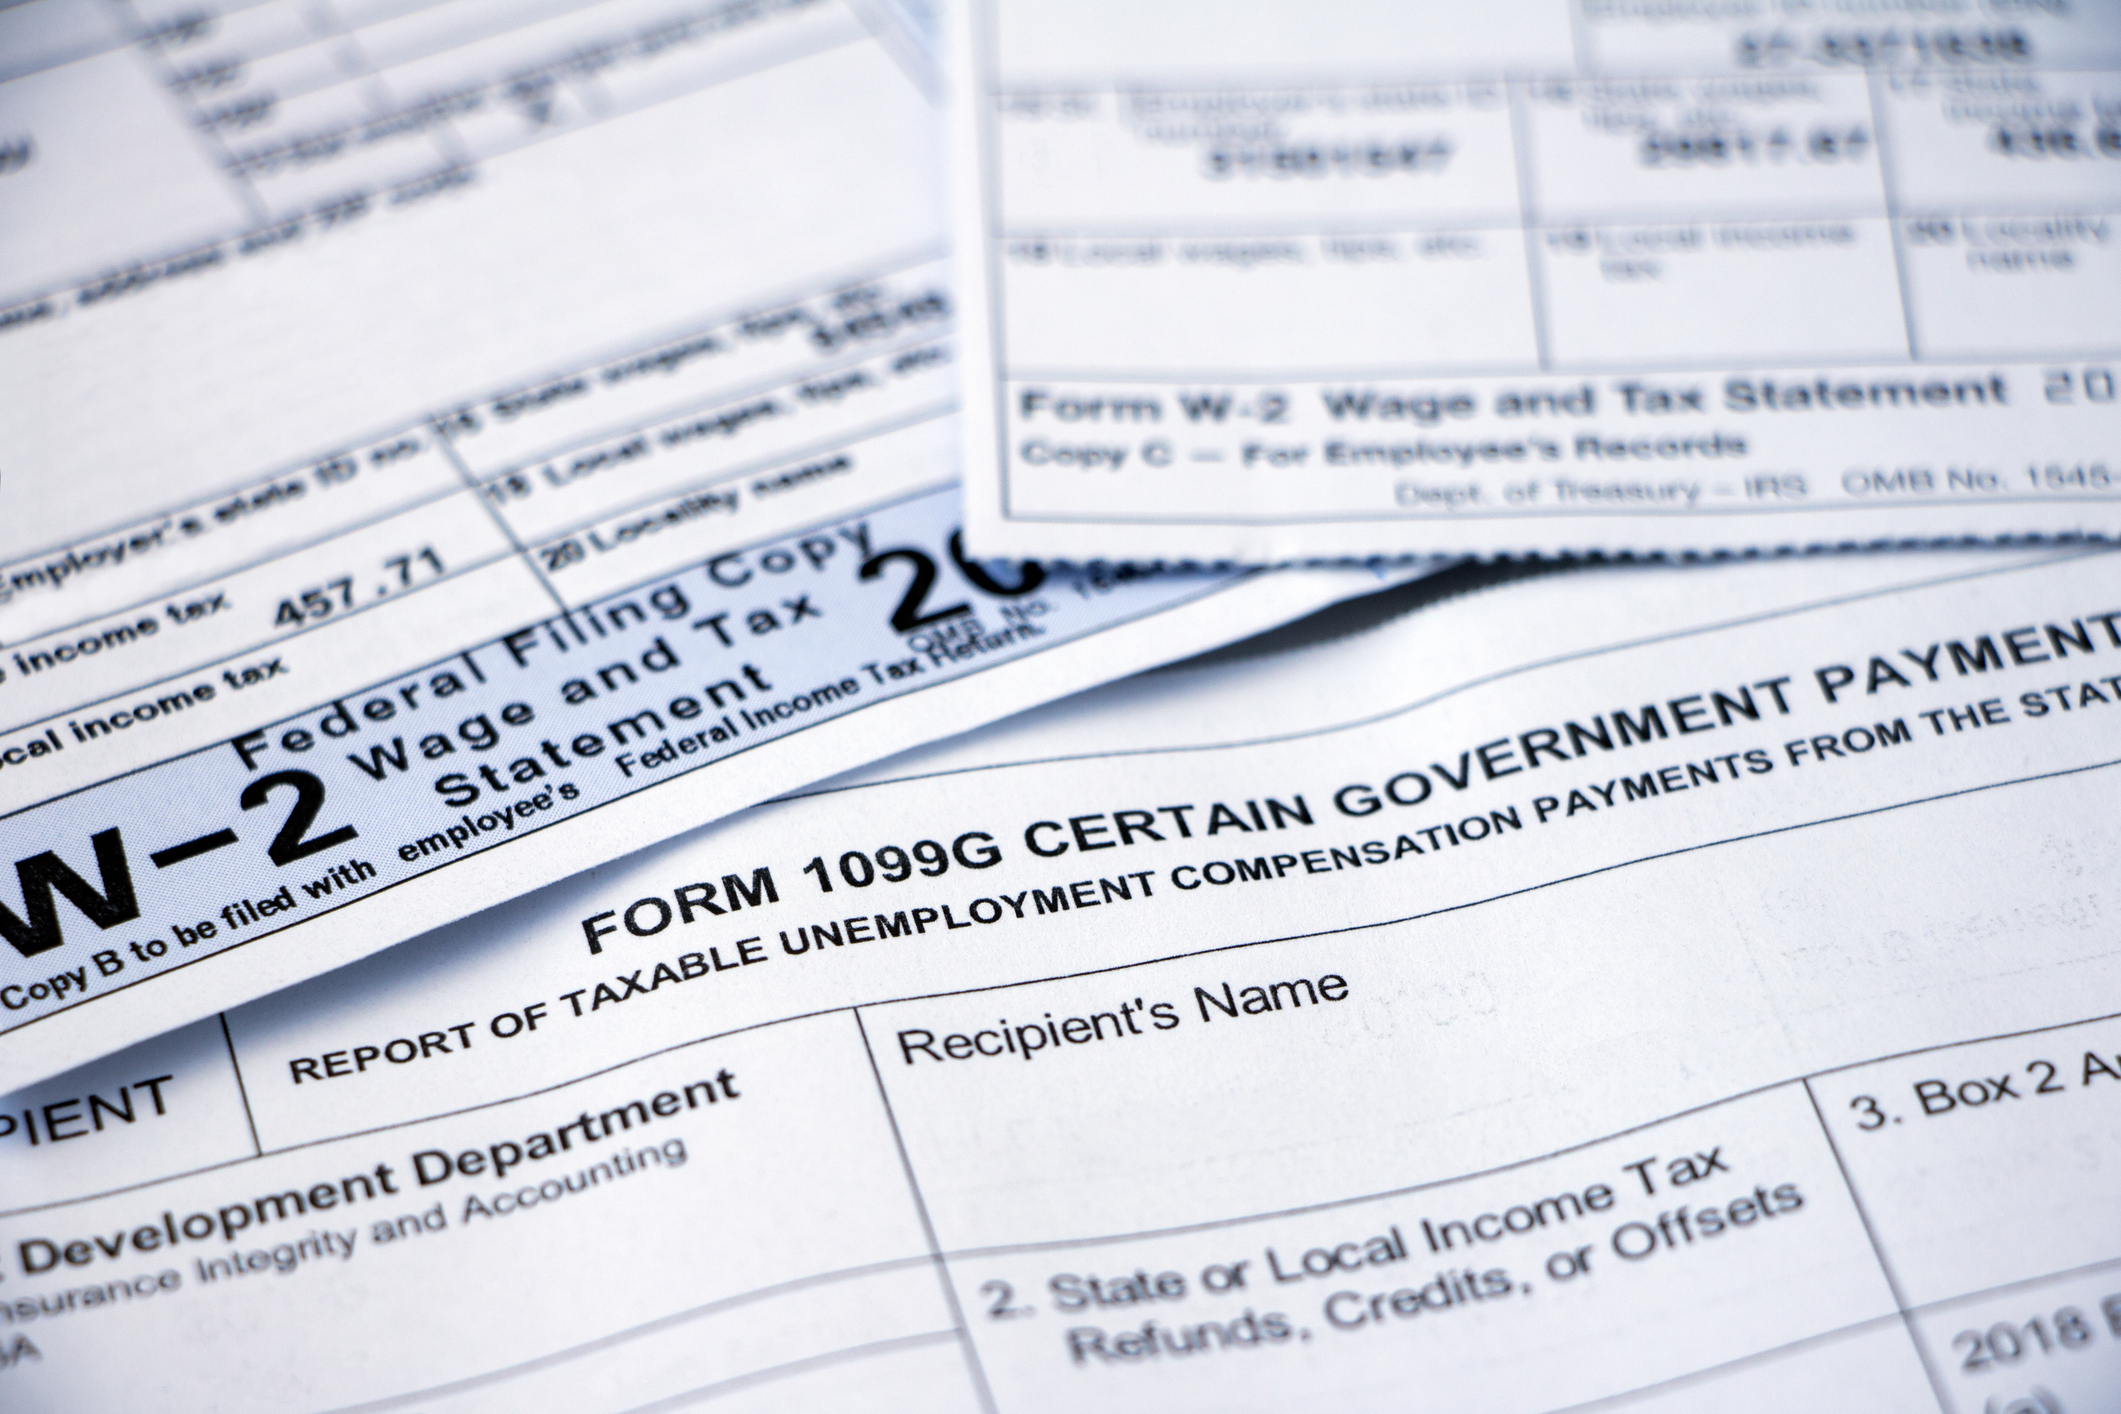
- Federal tax returns and W-2s for the relevant tax year
- Records of untaxed income (if applicable)
- Bank statements and investment records (as applicable)
- List of schools your student wants to receive the FAFSA information
If your family situation is more complex, you may also want documentation related to custody arrangements, child support, or significant income changes.
A note for mixed-status families: It is common for a student to be eligible for aid even if a parent is not. If a required contributor does not have an SSN, they can still complete their portion using the process the FAFSA provides. If you run into a technical roadblock, the school financial aid office can help you troubleshoot your next step.
Which tax year will we use?
FAFSA typically uses prior-prior year federal tax information. For example, the 2026–27 FAFSA generally uses 2024 tax data. If you are ever unsure, the FAFSA will indicate the specific tax year for that application cycle.
Main FAFSA steps
A quick timing tip: file as soon as the FAFSA opens for the school year your student will attend, especially if your state or colleges have priority deadlines.
Step 1: Start and enter student info
The student begins the form with personal details and school plans. Double check spelling, Social Security number entry, and date of birth. Small typos can create big delays.
Step 2: Add contributors
If the FAFSA determines parent or spouse information is required, the form will prompt you to invite contributors. This is where many families get stuck if they are rushing. Slow down and follow the instructions exactly.
Step 3: Confirm financial data
FAFSA uses tax and income data to estimate aid eligibility. For many filers, tax information is shared through the FAFSA Direct Data Exchange (rather than the older IRS Data Retrieval Tool terminology you may see online). When the form offers the secure data exchange option, use it if you can. It reduces errors and can lower the chances of extra back-and-forth later.
Step 4: Review and submit
Before you hit submit:
- Confirm names, dates of birth, and Social Security numbers
- Confirm marital status is accurate as of the day you file
- Confirm you selected the correct schools to receive the FAFSA
- Make sure every required signature and consent step is complete for the student and each contributor
After submission, you should receive confirmation. Save it or screenshot it for your records.
How many schools can you list? The FAFSA limits how many colleges you can include at one time. If you run out of room, you can submit first, then go back and replace schools so additional colleges can receive your information.
Deadlines to watch
There are usually multiple deadlines to keep in mind:
- The federal FAFSA deadline (a last possible date)
- Your state deadline (often earlier, and sometimes funds are first come, first served)
- Your college deadlines (can be tied to admissions, scholarships, or priority aid consideration)
My counselor tip: treat priority deadlines like the real deadline. In many cases, meeting priority dates can increase access to limited funds, especially at the state or campus level.
Common mistakes
- Waiting too long. Create FSA IDs and gather documents early, even if you will submit later.
- Entering the wrong marital status. FAFSA uses marital status as of the day you file, not the tax year you are using.
- Mixing up parent information in divorced or separated families. FAFSA rules generally look at which parent provided more financial support in the last 12 months. The FAFSA will guide you through who counts as a required contributor.
- Forgetting to list a school. If a school does not receive your FAFSA data, it cannot build a financial aid offer.
- Typing estimates when exact numbers are available. Use tax documents and official records whenever possible.
- Not finishing the signature and consent steps. An incomplete FAFSA can sit in limbo.
- Ignoring follow-up requests. Some students are selected for verification or other review.
If you get stuck
- Locked out of an FSA ID: start account recovery right away. It can take time, especially close to peak deadlines.
- A contributor did not receive an invite: confirm the email address exactly, check spam, and make sure the contributor’s FSA ID information matches what was entered.
- Identity verification delays: do not wait until the last week. Begin early and follow the requested steps carefully.
How aid offers work
This part can feel mysterious, so here is the most helpful mental model.
1) FAFSA creates a financial snapshot
The FAFSA uses income, assets, household size, and other factors to estimate a family’s ability to contribute. The result includes your Student Aid Index (SAI), which schools use as one input when building an aid offer.
2) Each school builds its own offer
Two colleges can look at the same FAFSA and offer very different packages because:
- Each school has different tuition and fees
- Some schools have more institutional grant money than others
- Some schools meet more financial need, while others may not
3) Offers mix gift aid and self-help
When you receive a financial aid package, look for the breakdown:
- Grants and scholarships (gift aid, does not need repayment)
- Work-study (earned through working, not guaranteed cash in hand)
- Student loans (borrowed money, must be repaid)
- Parent loans (optional, but also borrowed money)
If you only remember one thing: a good aid package is not just a big number. It is a package that keeps grants and scholarships high, and borrowing reasonable for your student’s expected future income.
After you submit
Watch for processing updates
After submission, your FAFSA is processed and sent to the schools you listed. If anything needs attention, respond quickly.
Know who asks for verification
If your file is selected for verification, the school (not the FAFSA itself) will contact you and request documents. This does not mean you did anything wrong. It just means you need to provide what they ask for by the deadline, which may include tax transcripts or other records.
Compare offers side by side
When offers arrive, compare:
- Total cost of attendance (not just tuition)
- Grants and scholarships vs. loans
- Renewal requirements for scholarships (GPA minimums, full-time enrollment, specific major requirements)
- Net cost after gift aid, not counting loans as discounts
If life changed, ask about professional judgment
If your family experienced a significant change like job loss, reduced hours, divorce, or medical expenses, contact the financial aid office and ask about a professional judgment review.
One helpful distinction: some requests are about special circumstances (usually financial changes). Others are about unusual circumstances, which can involve a dependency override when a student cannot provide parent information due to serious family conditions. The financial aid office can tell you what applies and what documentation is needed.
Quick FAQ
Is FAFSA only for low-income families?
No. While need-based grants depend on financial factors, many families file to access federal loans, qualify for certain scholarships, or keep options open.
Do we have to accept the loans offered?
No. You can accept all, some, or none of the aid offered. You can often reduce loan amounts before accepting.
What if my parents are uncomfortable sharing financial information?
That is common, especially for families who have not navigated U.S. college systems before. You can explain that the FAFSA is the standard gateway form for federal aid and widely used for state and school aid too. If a student is considered dependent for FAFSA purposes and parent information is required, leaving it out can limit aid eligibility significantly.
What if we made a mistake after submitting?
Corrections are often possible. Log back in, review the submission status, and follow prompts to update information. If you are unsure, the school financial aid office can tell you what to correct and what documentation might be needed.
A calm plan for this week
If you are not sure where to start, here is a simple three-step plan you can do in one evening:
- Step 1: Make a FAFSA folder and gather tax and identity documents.
- Step 2: Set up FSA IDs for the student and any required contributors.
- Step 3: Write down each college and your state priority deadline on one list, then plan to file as soon as FAFSA opens for your year.
Financial aid can feel like a maze, but it is a maze with signposts. Once your FAFSA is submitted, you are no longer guessing. You are in the system, and you can start making real, informed choices about college cost.